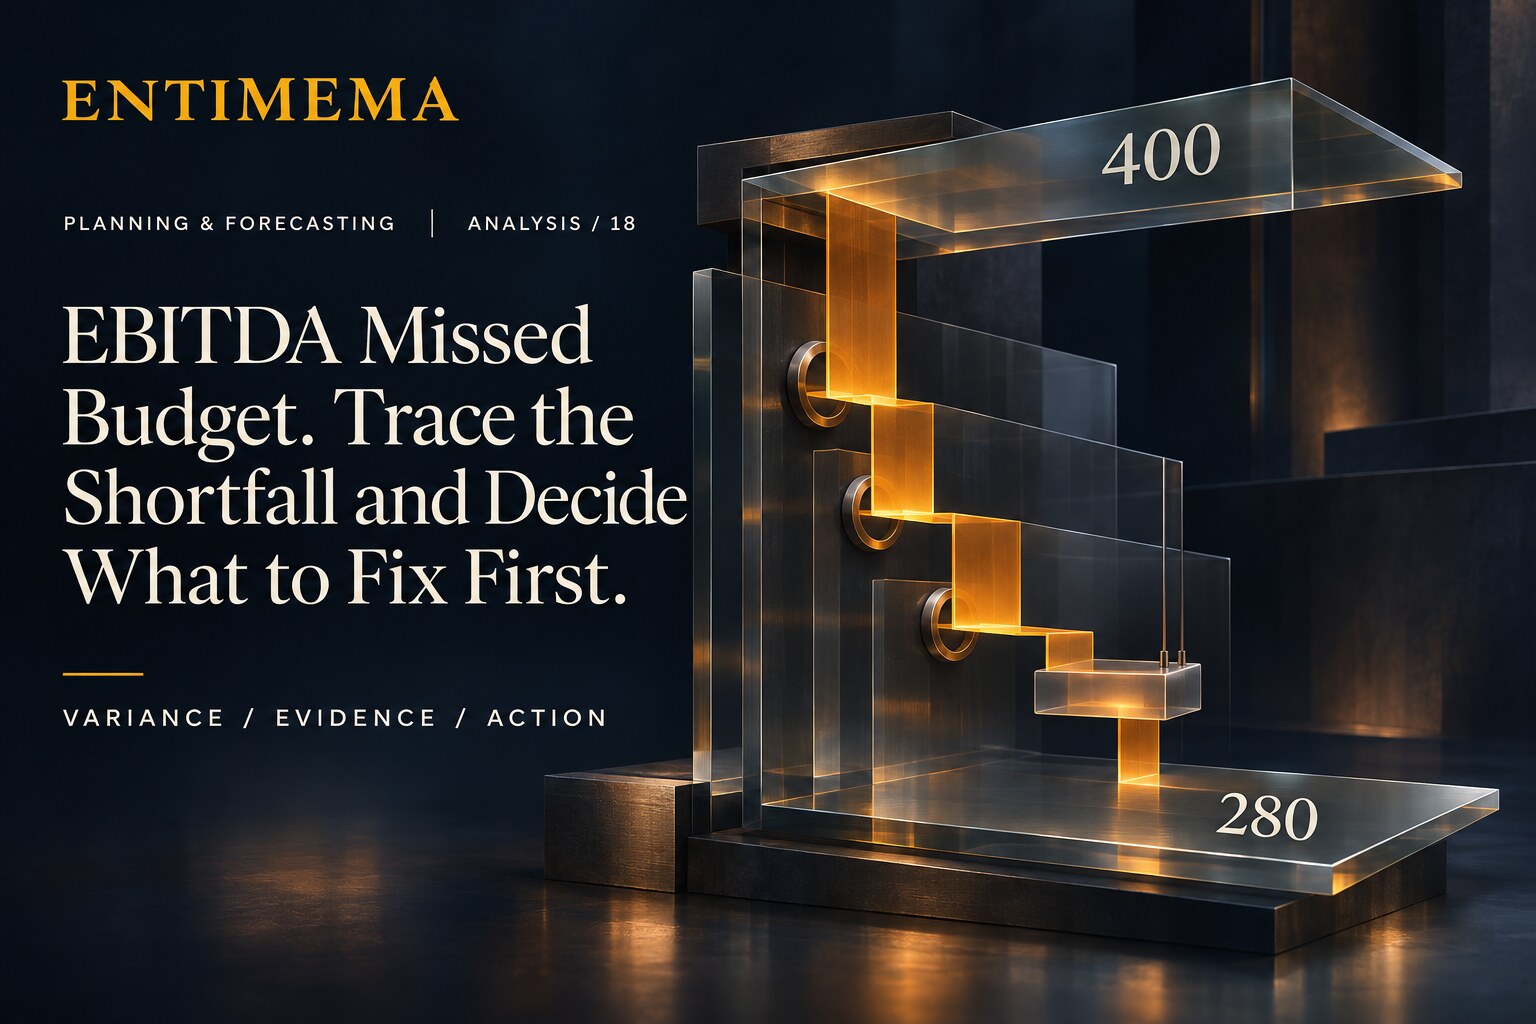
The monthly meeting opens with EBITDA of EUR 280 thousand against a budget of EUR 400 thousand. The management pack offers one sentence: “Lower volumes and higher production costs weighed on profitability.”
The statement is plausible, but it is not yet useful. It does not quantify the factors, distinguish accounting evidence from causal interpretation or tell management what can be changed before the next close. The CFO’s question is more exact: how much of the EUR 120 thousand shortfall comes from each driver, which explanations are verified, and where should the team intervene first?
A fluent sentence can conceal four different problems
“Lower volumes” may refer to fewer units sold, fewer units produced or an adverse product mix. “Higher production costs” could mean a purchase-price increase, excess physical consumption, an outdated standard, a timing difference or a classification change. Combining them in one sentence creates the appearance of explanation while preventing ownership.
| Required question | What the comment provides | What management still needs |
|---|---|---|
| How large is the miss? | Profitability was weaker | EUR 120k adverse versus budget |
| What caused it? | Volumes and production costs | A reconciled driver bridge |
| What is verified? | No evidence status | Source schedule and calculation for each material factor |
| What remains open? | No uncertainty | Explicit unresolved causal questions |
| What happens next? | No action | Owner, deadline and test of outcome |
The purpose of FP&A variance commentary is not to restate that actual differs from budget. It is to compress a controlled analysis into language that preserves the decision-relevant evidence.
How do you write budget vs actual variance commentary?
Write budget vs actual variance commentary by stating the result and comparison basis, reconciling the total variance into non-overlapping drivers, ranking the material verified factors, separating facts and calculations from unproven causes, and ending with a specific action, owner and review date. Every amount in the comment should link to a controlled schedule, and every causal claim should be labelled according to its evidence.
- Result: state actual, budget and the absolute or percentage variance with period, unit and sign convention.
- Drivers: reconcile the total through mutually exclusive price, volume, usage and operating-cost effects.
- Evidence: identify which factors are verified and which causal explanations still require review.
- Action: name the first intervention, accountable owner, deadline and next-cycle success measure.
The accounting result, calculated variance and causal hypothesis are different objects. Actual EBITDA is an accounted fact from the closed ledger. The EUR 30 thousand purchase-price effect is a deterministic calculation from quantity and price evidence. The proposition that energy inefficiency caused EUR 15 thousand is a hypothesis until operational checks support it.
Reconcile the EUR 120 thousand shortfall before explaining it
The following case is wholly synthetic and represents one monthly reporting period for a manufacturing company. All amounts are EUR thousands. A negative sign means an unfavourable effect on EBITDA; a positive sign would mean favourable.
| Step | Effect on EBITDA | EBITDA after effect |
|---|---|---|
| Budget EBITDA | — | 400 |
| Sales volume | −55 | 345 |
| Raw-material purchase prices | −30 | 315 |
| Energy usage variance | −15 | 300 |
| Operating expenses | −20 | 280 |
| Actual EBITDA | −120 versus budget | 280 |
The bridge reconciles: −55 − 30 − 15 − 20 = −120, and 400 − 120 = 280. That control proves completeness within the simplified bridge. It does not, by itself, prove that each factor was defined correctly or that the proposed cause is true.
Materiality determines what enters the executive comment. Here, sales volume and purchase price explain EUR 85 thousand, or 71% of the miss. Energy usage is smaller but potentially recurring. Operating expenses are material enough to disclose, although their mixed composition may require a separate schedule before an action is chosen.
Give every driver its own comparison basis
Double counting is avoided by holding all variables except the tested driver constant. The sequence is a policy choice and must be applied consistently; another valid convention may allocate interactions differently, but it must still reconcile to the same total.
| Driver | Comparison basis | Controlled calculation | Excluded from this line |
|---|---|---|---|
| Sales volume | Actual sales quantity versus budget quantity | Quantity difference × budget unit contribution | Price, mix and unit-cost movements |
| Purchase price | Actual purchase price versus budget price | Actual quantity purchased × price difference | Quantity, material usage and FX where separately reported |
| Energy usage | Actual energy consumed versus standard allowed for actual production | Usage difference × standard energy tariff | Tariff movement and output volume |
| Operating expenses | Actual expense versus budget after identified driver lines | Like-for-like residual by controlled cost category | Costs already allocated to volume, purchase price or energy usage |
Sales volume uses budget contribution so it does not absorb price or cost changes. Purchase price uses actual purchased quantity so the line isolates the price paid on the quantity actually bought. Energy usage compares actual consumption with the standard allowed for actual output, separating consumption from production volume and tariff. Operating expenses are added only after removing items already represented elsewhere.
The detailed decomposition method sits in Variance Analysis: Price, Volume, Mix and Cost Drivers. This article begins where that calculation ends: converting the reconciled bridge into defensible management commentary.
Trace the EUR 30 thousand purchase-price effect to its schedule
The controller selects one material raw-material line from the synthetic purchasing schedule. The quantity is tonnes and prices are EUR per tonne. The schedule is aligned to goods received in the reporting month; invoice timing differences are held in a separate accrual control.
| Evidence field | Budget | Actual | Variance input |
|---|---|---|---|
| Quantity purchased | 1,000 tonnes | 1,000 tonnes | Actual quantity = 1,000 |
| Price per tonne | EUR 500 | EUR 530 | Actual − budget = EUR 30 |
| Purchase value | EUR 500k | EUR 530k | EUR 30k adverse |
Purchase-price effect = actual quantity × (actual price − budget price) = 1,000 × (EUR 530 − EUR 500) = EUR 30,000 adverse.
The controller agrees 1,000 tonnes to the goods-receipt population, EUR 530 to purchase orders, invoices and accruals, and EUR 500 to the approved budget standard. The calculated EUR 30 thousand is then tied to the purchase-price row in the bridge. Quantity is not counted again because this line prices the actual quantity at the difference between actual and budget price; physical usage belongs to a separate consumption control.
Before the factor is described as supplier inflation, the controller should also test foreign-exchange treatment, freight and duty inclusion, supplier or grade mix, rebates, cut-off and whether the budget standard was current. The amount can be verified while the commercial reason remains more specific—or less certain—than the first narrative suggests.
The energy amount is calculated; its cause remains open
The EUR 15 thousand energy usage variance is calculated against the current standard allowed for actual production. Assume actual consumption exceeded that allowance and the excess, priced at the standard tariff, equals EUR 15 thousand. The bridge amount is arithmetically valid. Calling it “production inefficiency” would still overstate the evidence.
| Status | Statement | Evidence needed |
|---|---|---|
| Accounting fact | The period contains the recorded energy expense and metered consumption | Ledger, invoices and meter records |
| Calculated variance | Usage at standard tariff is EUR 15k adverse to the active standard | Actual output, metered usage, standard allowance and tariff |
| Open hypotheses | Mix shift, measurement issue, outdated norm, downtime or physical inefficiency | Production mix, meter completeness, standard version, downtime and batch-level consumption |
| Permitted comment | Energy usage was EUR 15k adverse; the operating cause is under review | No stronger causal wording until checks complete |
This is the failure mode that changes the management comment. “Energy inefficiency reduced EBITDA by EUR 15 thousand” sounds decisive but may send Operations after the wrong problem. The controlled wording preserves the measured variance and the unresolved question at the same time.
Release the comment only when the bridge and language pass control
| Control | Required result | Failure response |
|---|---|---|
| Result tie-out | Budget 400, bridge −120 and actual 280 agree to approved reporting views | Block the comment |
| Bridge reconciliation | Driver effects sum exactly to −120 | Find omission, duplication or residual |
| Baseline integrity | Period, scope, currency, unit and budget version are common | Restate the comparison |
| Driver exclusivity | Each effect has a defined counterfactual and no amount appears twice | Recalculate the bridge |
| Evidence trace | Material amounts link to source schedules and calculation logic | Mark unverified and withhold causal claim |
| Epistemic wording | Facts, calculated variances and causal hypotheses are distinguishable | Qualify the language |
| Action quality | Owner, deadline and next-cycle test are explicit | Return for decision completion |
A residual is not automatically an error, but it must be visible, defined and kept out of named drivers unless evidence supports its allocation. Commentary should be regenerated or re-approved when the underlying bridge changes; a previously approved sentence is not valid for a new model version.
The same result becomes a decision-ready CFO comment
| Version | Management commentary |
|---|---|
| Original | Lower volumes and higher production costs weighed on profitability. |
| Ready for the CFO pack | EBITDA was EUR 280k, EUR 120k below the EUR 400k budget. The shortfall reconciles to sales volume (EUR 55k adverse), raw-material purchase prices (EUR 30k adverse), energy usage at the active standard (EUR 15k adverse) and operating expenses (EUR 20k adverse). Volume and purchase-price effects are supported by the sales and purchasing schedules. The cause of the energy usage variance remains under review pending checks of production mix, metered consumption and the current standard. Procurement will address the verified purchase-price gap first and report contracted price coverage before the next close. |
The final comment contains the variance, the largest verified drivers, the open question and the first action. It avoids saying that all production costs are structurally higher or that energy inefficiency has been proven. It is short because the bridge and evidence carry the detail.
This is where the comment belongs in the finished management product: alongside the performance bridge, evidence status and owned actions shown in the Monthly Management Reporting Pack.
The CFO acts first where evidence and influence are strongest
| Decision | Owner | Deadline | Next-cycle verification |
|---|---|---|---|
| Prioritise the RM-4 purchase-price response: confirm negotiated price, contracted coverage and approved alternatives | Procurement Director | Within 10 working days, before the next close | Weighted purchase price versus EUR 500 budget standard; contracted coverage of next month’s requirement; realised EBITDA effect |
| Validate the EUR 15k energy usage cause before assigning an efficiency action or forecast persistence | Operations Controller | Within 5 working days | Reconciled mix-adjusted consumption, meter completeness and approved standard version |
| Decompose the EUR 20k operating-expense variance into recurring, timing and one-off items | Financial Controller | Before forecast refresh | Schedule reconciles to ledger and identifies owner and persistence for each material line |
| Review recovery plan for the EUR 55k volume shortfall without assuming margin-neutral replacement sales | Commercial Director | At the next weekly performance review | Order intake and volume outlook at budget contribution by product |
The CFO chooses the purchase-price response first because it is the largest verified unit-cost effect, the evidence is directly traceable, and Procurement can influence future purchases before the next closing cycle. The larger volume variance also requires action, but demand recovery may take longer and must be evaluated at contribution, not revenue alone. Energy remains an investigation until the causal evidence is strong enough to justify an operational intervention.
Reuse one disciplined structure every month
| Element | Prompt | Example form |
|---|---|---|
| Variance | What happened, against which basis and by how much? | EBITDA was [actual], [amount] [favourable/adverse] to [budget]. |
| Verified driver | Which material factors reconcile and what supports them? | The variance reconciles mainly to [driver and amount], supported by [schedule/control]. |
| Open question | Which causal explanation is not yet proven? | The cause of [variance] remains under review pending [specific evidence]. |
| Action and owner | What happens first, who owns it and by when? | [Owner] will [action] by [date], tested through [metric/evidence] next cycle. |
For the next report, confirm the reporting period, currency, unit, sign convention and approved budget version; reconcile the bridge to total variance; define a separate baseline for each driver; retain the calculation and source schedule; distinguish accounted facts, calculated effects and causal hypotheses; rank by materiality and controllability; and close with an owner, deadline and measurable review criterion.
Good management reporting variance commentary does not maximise certainty. It makes the boundary of certainty operational: management can act on the verified purchase-price effect, investigate energy without prejudging the cause, and measure whether the approved response changed the next result.